By Ed Drost — Maryland State Certified Residential Appraiser, License #30004874. Serving Baltimore City, Baltimore County, and Harford County for 36 years.
Most people find out what a home appraisal costs at the worst possible moment — when the closing paperwork is already in front of them and every line item feels like a surprise. After 36 years appraising homes across Baltimore, I can tell you the appraisal is one of the few closing costs you can actually plan for down to the dollar. This guide walks through where the appraisal fits in your Baltimore transaction, when the money is due, who typically pays, and how to budget for it without getting blindsided.
If you just want price ranges by property type, I keep those current on my Baltimore Home Appraisal Cost Guide — this article covers timing and budgeting, which is where most people get tripped up.
Where the appraisal falls in a Baltimore closing timeline
In a typical financed purchase, the appraisal is ordered shortly after your offer is accepted and the home inspection is underway — usually within the first week or two of the contract. Your lender orders it through an appraisal management company, and it needs to be completed and reviewed before the loan can move to final underwriting. In practical terms, that means the appraisal happens early enough that a low value still leaves room to renegotiate, but late enough that you're already emotionally attached to the house.
For a refinance, a PMI-removal request, or any non-lender appraisal I do directly — estate, divorce, tax appeal, pre-listing — the timing is yours to set, and the payment arrangement is simpler because there's no lender in the middle.
When the appraisal fee is actually due
This is the part that surprises Baltimore buyers most often: on a financed purchase, the appraisal fee is frequently collected up front, not rolled into closing. Many lenders charge it to the buyer's card within days of ordering, because the appraisal has to be paid for whether or not the deal ultimately closes. So even though it shows up on your Closing Disclosure as a closing cost, the cash often leaves your account weeks earlier.
Budget for it as an early, out-of-pocket expense — the same week as your home inspection — rather than something folded into the money you bring to the settlement table. If your deal falls through after the appraisal, that fee is generally not refundable because the work was already performed.
Who pays for the appraisal in Maryland?
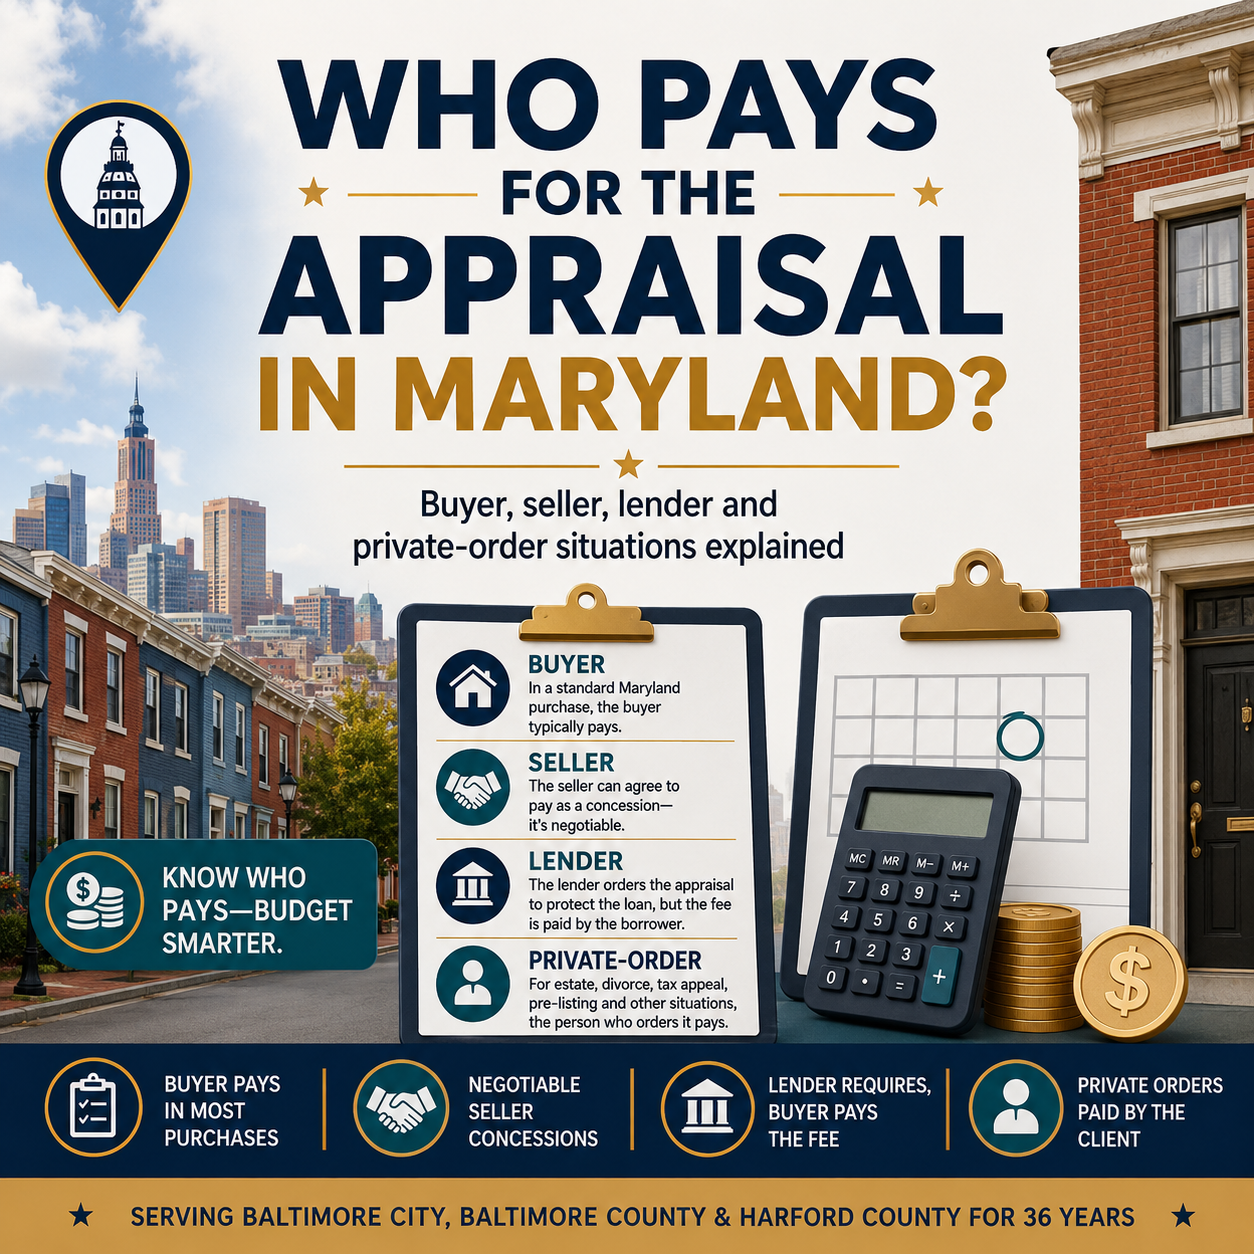
In a standard Maryland purchase, the buyer pays for the appraisal, because it's the buyer's lender requiring it to protect the loan. That's the default, but it's negotiable — I've seen plenty of Baltimore contracts where a motivated seller agrees to cover it as a concession, especially in a slower market. For the appraisals I perform directly for homeowners, the person ordering the report pays: the executor for an estate appraisal, either or both spouses for a divorce valuation, the homeowner for a tax appeal or pre-listing report.
How to build the appraisal into your budget
Here's the approach I'd give a family member buying in Baltimore:
Set aside the fee as a separate, early line item. Don't lump it into your "closing costs" mental bucket, because it usually comes due before closing. Treat it like the home inspection — a known cost you pay early in the process.
Match the amount to your property type. A standard Baltimore City rowhouse appraisal is priced differently than a waterfront home in Dundalk, a historic property in a CHAP district, or a small multifamily. The more complex the property, the more research the appraisal requires, and the range reflects that. My cost guide breaks the current ranges out by property type so you can budget the right number, not a generic estimate.
Budget for a second appraisal only if you're contesting value. If a purchase appraisal comes in low and you disagree, you can request a reconsideration of value through your lender, or — for non-lender situations like a tax appeal or divorce — commission an independent certified appraisal. Most buyers won't need a second report, but if you're in a legal or tax matter, plan for the possibility.
Why the certified appraisal is worth budgeting for
It's tempting to lean on a free online estimate or an agent's opinion and skip the cost. In a financed purchase you don't have that choice — the lender requires a certified appraisal. But even when it's optional, the appraisal is usually the cheapest insurance in the entire transaction. A few hundred dollars buys you an independent, USPAP-compliant opinion of value from a licensed professional whose report holds up with lenders, courts, and the IRS. Weighed against a home that's often the largest purchase of your life, that's a line item worth planning for rather than resenting.
Baltimore Appraisal Budgeting — Common Questions
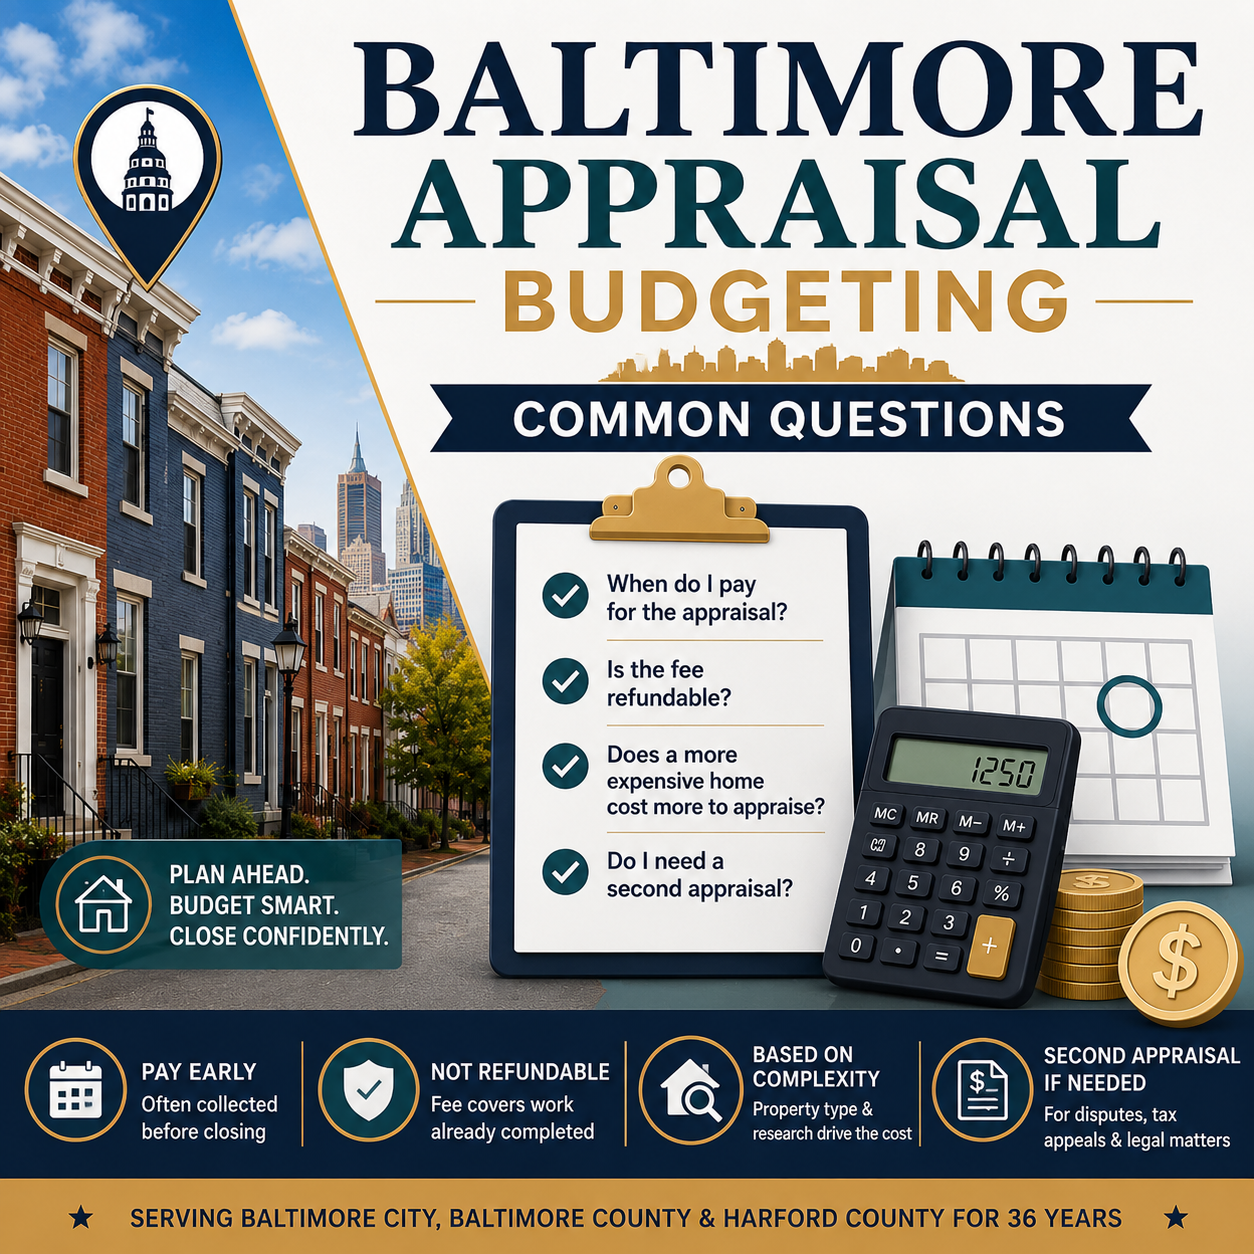
When do I pay for the appraisal in a Baltimore home purchase?
On most financed purchases, the appraisal fee is charged up front — often within days of your lender ordering it, weeks before closing. Although it appears on your Closing Disclosure as a closing cost, the cash usually leaves your account early, so budget for it alongside your home inspection rather than at settlement.
Is the appraisal fee refundable if my Baltimore deal falls through?
Generally no. The appraisal fee pays for work the appraiser has already performed — the inspection and the report. If the transaction collapses afterward, the fee is typically non-refundable because the service was completed. That's why it's smart to treat it as an early, committed expense.
Does a more expensive property mean a more expensive appraisal in Baltimore?
Not directly by price, but by complexity. A standard rowhouse is quicker to appraise than a waterfront home, a historic CHAP-district property, or a multifamily building, all of which require more research and comparable analysis. The fee reflects the work involved, not the home's value. See the current ranges by property type on my Baltimore Home Appraisal Cost Guide.
Planning a purchase, refinance, or PMI removal in the Baltimore area? I'll tell you exactly what your appraisal will cost for your specific property before you commit — no surprises. Call me directly at 443-904-5229, or see current pricing by property type on the Baltimore Home Appraisal Cost Guide.
Ed Drost is Baltimore's Trusted Appraiser — a Maryland State Certified Residential Appraiser (#30004874) with 36 years of experience across Baltimore City, Baltimore County, Carroll and Harford County — and an AI Visibility Architect helping professionals build authority in the age of AI search.
- Aug 21
How to Budget for Your Home Appraisal in a Baltimore Closing (2026)
- Ed Drost
- Baltimore's Trusted Appraiser
- 0 comments